If you are a veteran or active duty service member planning to build in Greater New Orleans, a New Orleans VA construction loan flood zone question is probably near the top of your list. South Louisiana is beautiful, but water shapes everything here, from where you can build to how high the slab or piers must sit. The good news is that the VA One-Time Close construction loan was built for exactly this kind of project, and with the right builder and plan, flood zone rules are something you prepare for, not something that stops you.
This New Orleans VA construction loan flood zone guide walks through how flood zones affect a VA One-Time Close (OTC) build in Orleans, Jefferson, St. Bernard, Plaquemines, St. Charles, St. John the Baptist, and St. Tammany parishes, plus the rest of the area within about 50 miles of the city.
What a New Orleans VA Construction Loan Flood Zone Plan Really Means
A VA One-Time Close loan combines your construction financing and your permanent mortgage into a single loan with a single closing. You sign once, the builder is paid through scheduled draws while the home goes up, and when the house is complete the loan simply converts to your long-term VA mortgage. There is no second closing and no second set of closing costs.
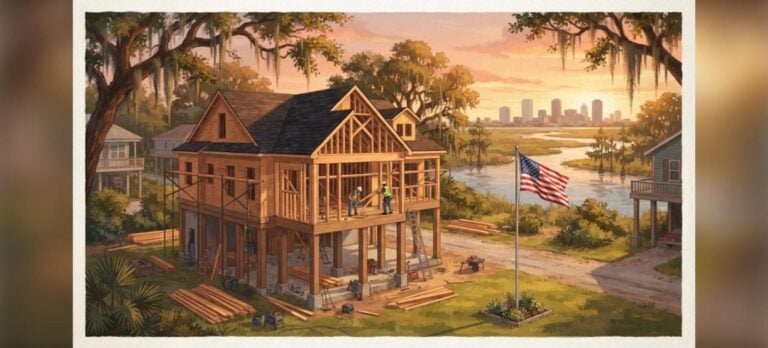
When the lot sits in a FEMA Special Flood Hazard Area (zones that start with A or V), the plan needs a few extra pieces:
- A design that places the lowest floor at or above the required elevation set by FEMA and your parish floodplain ordinance.
- An elevation certificate prepared by a licensed surveyor, often both during construction and at completion.
- A flood insurance policy in place before closing, with the cost built into your monthly payment.
- Plans and specs that the VA appraiser can value as a finished, code compliant home.
Many neighborhoods across the metro, including parts of the Northshore and the West Bank, are in zone X, where flood insurance is usually optional. Still, plenty of veterans in zone X choose a policy anyway because local rain events do not always follow the map.
Step 1: Confirm Your VA Eligibility and Entitlement
Everything starts with your Certificate of Eligibility (COE). Your lender can usually pull it in minutes. The COE shows your available entitlement, which matters because borrowers with full entitlement are not subject to a VA loan limit. That means eligible veterans and service members may be able to build with no down payment, subject to credit approval and the appraised value of the finished home.
VA loans also have no private mortgage insurance (PMI). Instead, most borrowers pay a one-time VA funding fee, which can be financed into the loan. Veterans who receive VA compensation for a service-connected disability are exempt from the funding fee, and so are active duty service members who have received a Purple Heart. On a new build, that exemption can save thousands of dollars.
Step 2: Choose a VA Registered Builder Who Knows Flood Construction
For a VA One-Time Close loan, your builder must have a VA builder ID and meet the lender’s builder approval standards, which typically include licensing, insurance, financials, and references. In Greater New Orleans, also ask every builder you interview:
- How many raised or pier and beam homes have you built in the last three years?
- Do you work with a surveyor for elevation certificates at the form survey and at completion?
- How do you handle drainage, fill, and slab height on lots near a levee or canal?
- What wind and hurricane strapping standards do you build to?
A builder who answers these with confidence will usually make your New Orleans VA construction loan flood zone file smoother during underwriting and the VA appraisal.
Step 3: Check the Flood Map Before You Buy the Lot
Before you put money down on land, look up the address on the FEMA Flood Map Service Center and call the parish permit office to confirm the required base flood elevation and any local freeboard. Freeboard is extra height above the base flood elevation that some parishes require or encourage. Building higher can raise construction costs, but it may also lower flood insurance premiums over the life of the loan.
If you already own the lot, the equity in the land may be able to count toward the project, and the remaining lot payoff can often be rolled into your VA OTC loan. Your loan advisor can review the details of your New Orleans VA construction loan flood zone situation.
Step 4: Budget for Flood Insurance in Your VA Construction Loan
Flood insurance is one of the biggest wildcards for a New Orleans VA construction loan flood zone budget. Under FEMA’s current rating method, premiums depend on things like elevation, distance to water, foundation type, and rebuilding cost rather than just the zone letter. Get an insurance quote early, using the builder’s plans, so your monthly payment estimate is realistic before you sign a construction contract.
Homeowners insurance with wind coverage is also required. In coastal Louisiana, ask your agent about fortified roof construction and any available discounts, then share that information with your builder before plans are final.
Step 5: The VA Appraisal and Minimum Property Requirements
The VA appraiser values the home based on your plans and specifications as if it were complete. When construction is finished, the home must meet VA Minimum Property Requirements (MPRs), which focus on safety, soundness, and sanitation. A final inspection confirms the home was built as planned before the loan converts to permanent financing. On a New Orleans VA construction loan flood zone build, keep the final elevation certificate and flood policy ready for the file. For the official program overview, visit the VA home loans page.
Step 6: Plan Your Build Timeline Around Hurricane Season
Most single-family builds in the area take roughly six to twelve months, depending on permits, weather, and materials. Raised homes add steps like pilings or piers and extra inspections. Many veterans try to have framing and roofing done before the peak of hurricane season, which runs from August through October. Your builder’s draw schedule and the lender’s inspection process will set the pace once ground breaks.
Step 7: Keep Your Credit and Finances Steady Until Closing
Because a VA One-Time Close loan has one closing before construction begins, your construction and permanent financing are set up together at the start. Even so, avoid opening new credit or making large purchases while you are in process. Keep documentation handy for income, service history, and the lot. Clear communication with your loan advisor and builder keeps the project moving.
Why Veterans Choose a VA One-Time Close Loan in New Orleans
For eligible veterans and active duty members, the VA OTC loan can offer a lot in one package: no down payment for borrowers with full entitlement, no PMI, one closing, and funding fee exemptions for those with a service-connected disability rating. When your lot falls in a New Orleans VA construction loan flood zone area, the core benefits stay the same. You simply plan the elevation, insurance, and builder details up front.
Every situation is different, and all loans are subject to credit approval and program guidelines. If you want to talk through your eligibility, your lot, or your builder, Max Mortgage is here to help you understand each step. Learn more at Max Mortgage.
New Orleans VA construction loan flood zone FAQ
Can I use a VA One-Time Close loan if my lot is in flood zone AE?
In many cases, yes. A New Orleans VA construction loan flood zone project in zone AE usually needs a design built to the required elevation, an elevation certificate, and flood insurance in place before closing. Approval depends on the property, the builder, and program guidelines.
Does the VA funding fee apply to my construction loan?
Most borrowers pay the VA funding fee, and it can be financed. Veterans receiving VA compensation for a service-connected disability are exempt, which can make a New Orleans VA construction loan flood zone build more affordable.
Do I need a down payment to build with a VA loan in New Orleans?
Eligible veterans and active duty borrowers with full entitlement may be able to build with no down payment, subject to credit approval and the appraised value of the completed home.
Talk With Us About Your New Orleans VA Construction Loan
- 24/7 prequalification hotline: 504-399-4141
- 24/7 application hotline: 504-332-0888
Written by Charles, Mortgage Loan Advisor with Max Mortgage, LLC. 20+ years in mortgage and real estate. NAMB Certified FHA Mortgage Professional.
Equal Housing Opportunity. This is not a commitment to lend or extend credit. Restrictions may apply. Information and/or data is subject to change without notice. All loans are subject to credit approval. Not all loans or products are available in all states. Licensed in LA, TX, MS, AL, FL. Max Mortgage, LLC NMLS #1446745