You found the house. Maybe it is a raised center hall in Gentilly, a shotgun double in the Bywater, or a brick ranch on the Northshore. Your offer was accepted, and now the next big milestone is the New Orleans VA appraisal.
For many veterans and active duty buyers, this is the step that feels the most mysterious. Who orders it? What is the appraiser looking at? What happens if the value comes in under your contract price? This guide walks through the process in plain language so you know what to expect and what comes next.
What a New Orleans VA Appraisal Actually Does
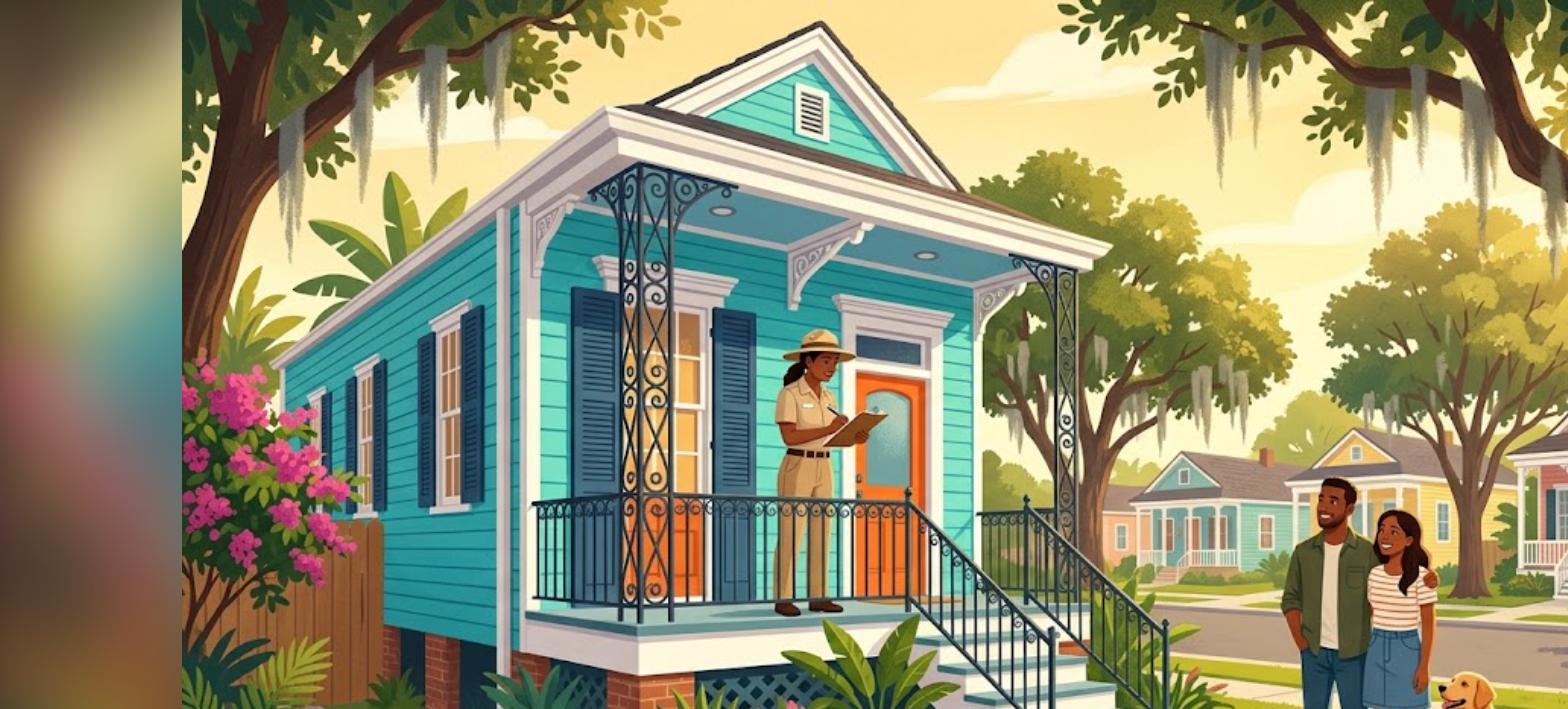
A VA appraisal has two jobs. First, it estimates the market value of the home by comparing it to recent nearby sales. Second, it checks that the home meets the VA’s Minimum Property Requirements, often called MPRs. Those requirements focus on whether the home is safe, structurally sound, and sanitary.
Your lender orders the appraisal through the VA’s own system, and the VA assigns an independent, VA approved appraiser. You do not get to pick the appraiser, and neither does the seller or the real estate agent. That independence is part of what protects you.
One important point: a New Orleans VA appraisal is not a home inspection. The appraiser is not crawling into the attic to test every outlet. A separate home inspection is still a smart move, especially with older housing stock.
Minimum Property Requirements in Older New Orleans Homes
New Orleans has some of the most beautiful historic homes in the country. It also has plenty of homes that are 80 or 100 years old. That character is great, but it means your New Orleans VA appraisal may flag items a newer suburban home would never trigger.
Common items the appraiser looks at include:
- Roof condition. The roof should keep moisture out and have reasonable remaining life.
- Peeling paint. In homes built before 1978, chipping or peeling paint is treated as a possible lead hazard and usually has to be corrected.
- Heating and electrical. Systems should work safely. Exposed or damaged wiring is a common flag.
- Water and sewer. The home needs safe, working plumbing and a proper connection to water and sewer.
- Foundation and piers. Raised homes on piers are common here. The appraiser will note settling, rot, or damage that affects safety.
- Crawl space access and ventilation. Moisture under a raised home is a real concern in our climate.
If something does not meet MPRs, your New Orleans VA appraisal will list it as a condition. The repair usually needs to be completed and verified before closing. Who pays for the repair is something you and the seller negotiate. The VA does not require the seller to pay.
Termites and the Wood Destroying Insect Report
Louisiana sits in a high termite risk area, and Formosan termites are a well known problem in the New Orleans region. Because of that, a Wood Destroying Insect report, often called a WDI or termite report, is typically part of the process for a VA purchase here.
A licensed pest inspector completes the report, separate from the New Orleans VA appraisal itself. If active infestation or damage shows up, it generally needs to be treated and, when needed, repaired before the loan can close. On a VA loan, veterans are limited in which closing fees they can pay, so talk with your agent early about how the termite report will be handled in your contract.
How the New Orleans VA Appraisal Estimates Value
For the value side, the appraiser looks at comparable sales, usually recent closed sales of similar homes nearby. In a city where two homes on the same block can be completely different, this is where things get interesting.
A renovated camelback and an original condition double can sit side by side and sell for very different prices. Elevation, flood zone, off street parking, and lot size can also move value. A good appraiser familiar with local neighborhoods helps a lot, and that is one reason the VA assigns appraisers by area.
The result of a New Orleans VA appraisal is a Notice of Value, sometimes called an NOV. This is the official value the VA uses for your loan.
The Tidewater Process: An Early Warning
Here is a VA feature many buyers never hear about. If the appraiser believes the value will come in below the contract price, they are expected to give a heads up before finishing the report. This is called the Tidewater process.
Once Tidewater is triggered, your agent and lender typically have about two business days to send the appraiser additional comparable sales that support the price. If those comps are strong, the value may come in where it needs to be. If not, the appraiser finalizes the report at the lower figure.
This is one reason it helps to have an agent who knows the neighborhood and can pull solid comps quickly.
What If Your New Orleans VA Appraisal Comes In Low?
A low value is stressful, but you have options. The VA bases its loan on the lower of the appraised value or the contract price, so a gap has to be handled somehow. Common paths include:
- Renegotiate with the seller. Many sellers will lower the price rather than lose the deal.
- Request a Reconsideration of Value. A formal ROV lets you submit additional sales or correct factual errors in the report.
- Cover the difference in cash. You can choose to pay the gap yourself, though you are not required to.
- Walk away. VA purchase contracts include a required amendment, often called the escape clause, that lets you cancel without losing your earnest money if the value comes in below the price.
That escape clause is a real protection. A low New Orleans VA appraisal does not force you to overpay for a home.
How Long a New Orleans VA Appraisal Takes
Timing depends on appraiser workload, access to the home, and whether repairs are needed. Plan for the appraisal step to take a week or more, and build some cushion into your contract dates. If the report lists repairs, the re-inspection adds time. Clear communication between your agent, the seller, and your loan team keeps things moving.
Tips to Prepare for Your New Orleans VA Appraisal
- Ask your agent to share a list of recent upgrades with the appraiser, such as a new roof, HVAC, or elevation work.
- Make sure utilities are on so systems can be checked.
- Clear access to the attic, crawl space, and electrical panel.
- Walk the house for peeling paint, missing handrails, or broken windows before the New Orleans VA appraisal visit.
- Request an elevation certificate from the seller if the home has one. It helps with flood insurance pricing too.
- Get your homeowners and flood insurance quotes early, so your budget reflects real numbers.
If you are still mapping out the full cost of buying, our guide to New Orleans VA closing costs is a helpful next read. For the official program overview, visit the VA Home Loans page from the Department of Veterans Affairs.
The Bottom Line on a New Orleans VA Appraisal
A New Orleans VA appraisal is there to protect you. It checks that the home is safe and that you are not paying more than the market supports. Knowing about MPRs, the termite report, Tidewater, and the escape clause puts you in a much stronger position.
Every appraisal and every property is different, and all loans are subject to credit approval. If you have questions about your situation, reach out any time.
Get Started Today
- 24/7 prequalification hotline: 504-399-4141
- 24/7 application hotline: 504-332-0888
Charles, Mortgage Loan Advisor with Max Mortgage, LLC. 20+ years in mortgage and real estate. NAMB Certified FHA Mortgage Professional.