New Orleans FHA home loans come with one step that surprises many first-time buyers: the FHA appraisal. You found a house you love in Uptown, Gentilly, Algiers, Metairie or Kenner, your offer was accepted, and then an appraiser walks the property with a very specific checklist. Knowing what that person looks for can save you stress, money and weeks on the calendar.
This guide explains how the appraisal works, what the appraiser flags on older New Orleans homes, how flood zones change the math, and how to protect your deal before you ever write an offer.
How the Appraisal Works for New Orleans FHA home loans
Every one of the New Orleans FHA home loans requires an appraisal from an FHA-approved appraiser. The appraiser does two jobs at once. First, they estimate the market value of the home. Second, they confirm the property meets HUD minimum property requirements for safety, security and soundness.
That second job is what makes New Orleans FHA home loans different from many other loan types. The home is not just collateral for the lender. It also has to be a safe place for you to live.
The appraiser is not a home inspector. The appraisal is not a full inspection, and it will not catch every hidden problem. This is why we always encourage buyers of New Orleans FHA home loans to hire their own licensed inspector as well.
What Appraisers Flag on New Orleans Homes
New Orleans has a beautiful and very old housing stock. Charm comes with maintenance, and these are the items that most often show up in an FHA report:
- Peeling or chipping paint. On homes built before 1978, deteriorated paint can be a lead-based paint concern and usually has to be scraped and repainted by a qualified contractor before closing.
- Roof condition. The roof should have a reasonable remaining life, commonly about two years or more, and no active leaks.
- Missing handrails and unsafe steps. Raised porches and front stairs are common here, so railings matter.
- Exposed wiring or outdated panels. Safety hazards in the electrical system can be called out.
- Termite and wood damage. Active infestation or rot in structural wood often needs treatment and repair.
- Foundation and drainage issues. Standing water, settling and poor grading draw attention.
Many of these items are fixable with New Orleans FHA home loans. If the appraiser lists repairs, the seller can complete them, you and the seller can negotiate who pays, or in some cases funds can be held back to complete the work after closing. Your loan advisor can walk you through each option for your specific New Orleans FHA home loans file.
Flood Zones and Flood Insurance for New Orleans FHA home loans
In the New Orleans area, flood risk is part of nearly every home purchase. If the property sits in a FEMA Special Flood Hazard Area, flood insurance is required on an FHA loan. You can look up any address for free at the FEMA Flood Map Service Center.
With New Orleans FHA home loans, flood insurance premiums can change your monthly payment as much as the interest rate does. That is why we recommend getting a flood insurance quote before you make an offer. Ask the seller for an elevation certificate if one exists, since it can lower your premium.
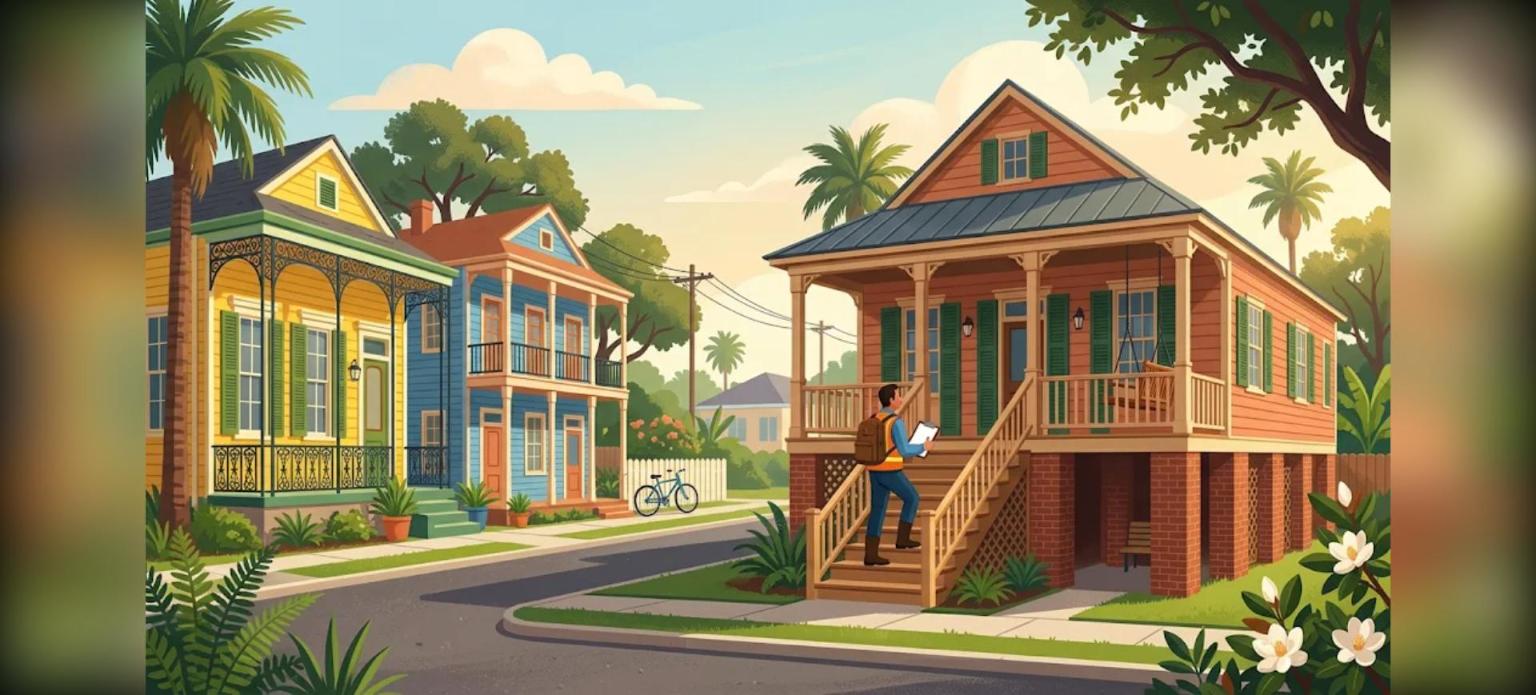
Pro tip: a home that sits higher, such as a raised cottage on piers, often costs less to insure than a slab-on-grade house on the same street. Ask your insurance agent to compare.
Appraisal Timing and Costs
For New Orleans FHA home loans, plan for the appraisal to be ordered shortly after your contract is accepted. The buyer typically pays the appraisal fee, and in the greater New Orleans area it commonly runs in the range of several hundred dollars, depending on the property. Turn times can stretch during busy seasons, so build a little cushion into your closing date.
An FHA appraisal is generally valid for 120 days, which is helpful if closing gets delayed by repairs or insurance. For a deeper look at the monthly costs that come with the loan, read our guide to New Orleans FHA mortgage insurance costs.
What If the Appraisal Comes in Low?
When the appraised value is lower than the contract price, the loan amount is based on the lower number. You generally have three choices: ask the seller to reduce the price, bring extra cash to cover the gap, or request a review with new comparable sales. It is also possible to walk away under the terms of your contract.
The best defense on New Orleans FHA home loans is a realistic offer. Your agent can pull recent sales on your street, and we can run your numbers so you know your payment before you commit.
Loan Limits, Credit and Down Payment Basics
New Orleans FHA home loans are popular with first-time buyers because of their flexible guidelines. In 2026 the FHA loan limit for a one-unit home in Louisiana is $541,287, and it applies to every parish. Qualifying scores and down payment minimums depend on your full profile, so a quick conversation is the fastest way to find out where you stand.
The official rules for FHA properties are published by HUD in its Single Family Housing Policy Handbook, and your advisor reads them every day so you do not have to.
A Simple Checklist Before You Make an Offer
- Get prequalified so you know your price range and monthly payment.
- Choose an agent who understands New Orleans FHA home loans and older homes.
- Check the flood zone and request an insurance quote on the address.
- Ask about the age of the roof, wiring and paint during the showing.
- Hire your own inspector and review the report before the appraisal.
Each step lowers the odds of surprises later with New Orleans FHA home loans. Buyers who prepare this way tend to close with fewer delays.
Talk With a Loan Advisor Before You Shop
New Orleans FHA home loans are not hard when you know the road ahead. The appraisal, the flood zone and the property standards are all manageable with a plan, and the right preparation lets you shop with confidence in Orleans, Jefferson and the surrounding parishes.
Ready to see what you qualify for? Call or text one of our hotlines, available around the clock:
- 24/7 prequalification hotline: 504-399-4141
- 24/7 application hotline: 504-332-0888
Charles, Mortgage Loan Advisor with Max Mortgage, LLC. 20+ years in mortgage and real estate. NAMB Certified FHA Mortgage Professional.