New Orleans DSCR 1-4 unit duplex financing is one of the most practical ways for a New Orleans investor to buy a rental without proving personal income. A DSCR loan, short for debt service coverage ratio, qualifies the property by its rent. If you are buying your first rental or adding to a portfolio, this guide explains how it works across Orleans, Jefferson, St. Tammany, and the surrounding 50 miles.
How New Orleans DSCR 1-4 Unit Duplex Financing Works
With New Orleans DSCR 1-4 unit duplex financing, the lender compares the monthly rent to the monthly housing payment. That payment includes principal, interest, taxes, insurance, and any association dues. The result is your DSCR.
A ratio of 1.0 means the rent covers the payment exactly. Many lenders like to see 1.0 or higher, and some programs allow lower ratios with stronger credit or more cash down.
Because the property qualifies the loan, there are usually no tax returns, no W-2s, and no debt-to-income ratio to document. That is why New Orleans DSCR 1-4 unit duplex financing appeals to self-employed buyers and to investors who already show heavy write-offs.
What Counts as a 1-4 Unit Property in New Orleans
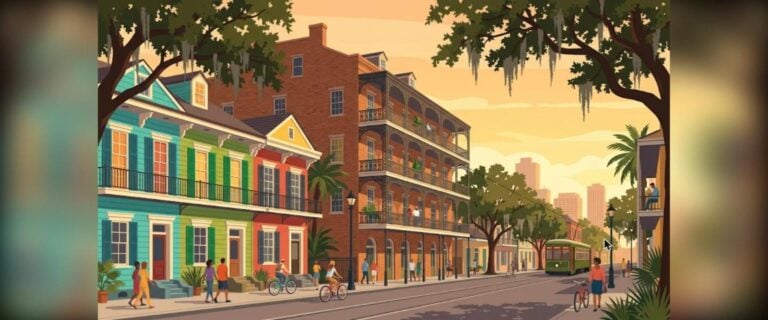
The 1-4 unit category covers single-family rentals, duplexes, triplexes, and fourplexes. In New Orleans, that includes the classic double shotgun, the side-by-side Creole cottage, and small brick fourplexes found in neighborhoods such as Mid-City, Gentilly, Bywater, and Algiers.
Many of these buildings sit on one lot with one deed. That makes them straightforward to finance with New Orleans DSCR 1-4 unit duplex financing, as long as the property is a rental and not your primary home.
Rental Income Rules Investors Should Know
The rent used for qualifying comes from one of two places. For a leased unit, the lender typically uses the signed lease. For a vacant or newly purchased unit, the appraiser provides a market rent estimate.
For a duplex, you add the rent from both sides. For a fourplex, you add all four. This is where New Orleans DSCR 1-4 unit duplex financing can work well, since more doors often means more rent against one mortgage payment.
Short-term rentals add a wrinkle. Some programs will use projected short-term income, while others want a long-term lease. Ask before you write an offer.
Down Payment, Credit, and Reserves
Every investor wants to know what cash is needed. These are common starting points for New Orleans DSCR 1-4 unit duplex financing, though terms vary by scenario:
- Down payment: often 20 to 25 percent for an investment purchase.
- Credit score: many programs start in the 660 to 680 range, with better pricing at higher scores.
- Reserves: lenders commonly ask for several months of the full payment in liquid funds.
- Property type: single-family, 2-unit, 3-unit, or 4-unit residential rental.
Stronger rent, higher credit, and more cash down can improve your rate. A thin DSCR can still work, but expect a larger down payment and a higher rate.
A Simple DSCR Example for a New Orleans Duplex
Say you find a duplex where each side rents for $1,500 a month. Total rent is $3,000. If the full payment with taxes and insurance is $2,500, the DSCR is 1.2.
That is a healthy ratio for New Orleans DSCR 1-4 unit duplex financing. If insurance climbs, which is a real issue in Louisiana, the ratio drops. Always quote the real insurance premium early so the numbers are not a surprise at closing.
Why Investors Choose DSCR Over a Conventional Loan
A conventional investment loan counts your personal income and your other debts. Each new rental can push your debt-to-income ratio higher and slow you down. New Orleans DSCR 1-4 unit duplex financing sidesteps that, so you can keep adding doors as long as each property carries itself.
It also helps first-time investors who have strong savings but a short or irregular income history. The loan follows the rent, not your paycheck.
Steps to Close a DSCR Loan on a 1-4 Unit Property
- Get prequalified so you know your price range and cash needed.
- Find a duplex or fourplex and estimate rent and insurance.
- Submit a contract and request an appraisal with a rent schedule.
- Review the DSCR and final terms, then close in an LLC if your advisor and attorney agree it fits your plan.
Talk with your insurance agent and attorney about entity structure, flood zones, and local rental rules. A lender cannot give legal or tax advice, and New Orleans has short-term rental regulations worth reading. The Louisiana Office of Financial Institutions is a good public resource for lender licensing questions.
Talk to a Mortgage Loan Advisor About Your Next Rental
If New Orleans DSCR 1-4 unit duplex financing fits your plan, start with a quick prequalification. You can also visit the Max Mortgage home page to learn about other programs.
24/7 prequalification hotline: 504-399-4141
24/7 application hotline: 504-332-0888
Charles, Mortgage Loan Advisor with Max Mortgage, LLC. 20+ years in mortgage and real estate. NAMB Certified FHA Mortgage Professional.
Equal Housing Opportunity. This is not a commitment to lend or extend credit. Restrictions may apply. Information and/or data is subject to change without notice. All loans are subject to credit approval. Not all loans or products are available in all states. Licensed in LA, TX, MS, AL, FL. Max Mortgage, LLC NMLS #1446745