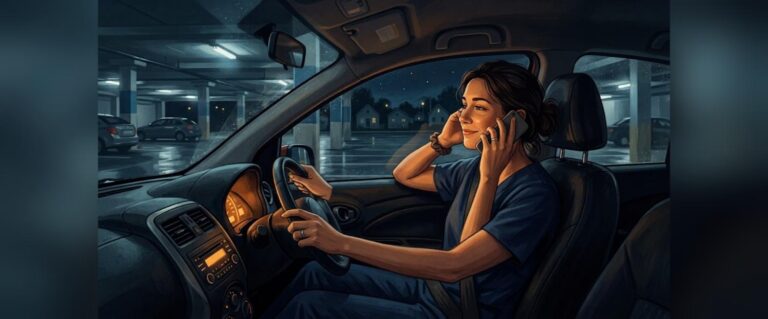
Mortgage prequalification for shift workers is available 24 hours a day at 504-399-4141, the Max Mortgage prequalification hotline. The line is answered by Dana, an automated AI assistant, not a person, and it does not close at 5pm. If you work nights, swing shifts, rotating schedules, or holiday coverage, you can call when you are actually awake and get a sense of which loan programs may fit your situation. A licensed Max Mortgage team member follows up afterward.
That last part matters more than it sounds. The single most common reason people put off the first mortgage conversation is not fear of the answer. It is that the phone lines are open exactly when they are unavailable to use them.
Why Mortgage Prequalification for Shift Workers Never Fit the Old Schedule
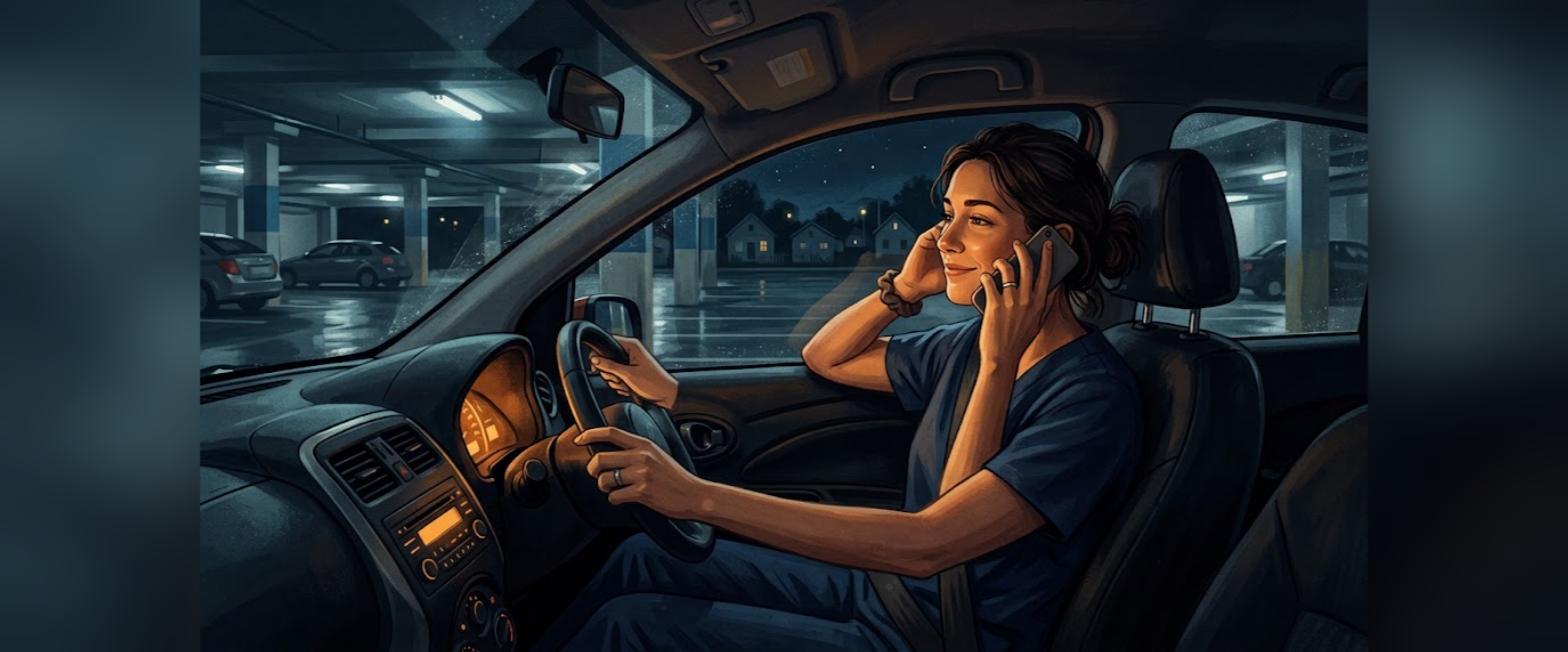
Consider a med-surg nurse on three twelve-hour nights. She clocks in at 7pm and out at 7:30am. Lender business hours are 9am to 5pm. Her sleep runs roughly 9am to 4pm. The overlap between when she is conscious and when a loan office is staffed is about an hour, and that hour is the one she uses for errands, appointments, and everything else a normal person handles in daylight.
Now multiply that across the people who keep a city running. Offshore crews on hitch. Refinery and plant operators. Longshoremen and port workers. Hotel and restaurant staff working nights through Carnival and festival season. Police, fire, and EMS on 24-hour rotations. Warehouse and distribution workers on overnight pulls. Baggage handlers and ramp agents. Casino floor staff. Anyone whose weekend lands on a Tuesday.
In the New Orleans and Baton Rouge market, that is not a niche. It is a large share of the workforce. The traditional mortgage schedule was simply built for someone else.
A Hotline That Matches Your Hours, Not Ours
Max Mortgage put the prequalification line at 504-399-4141 on a 24 hour clock for a straightforward reason. The calls were already coming in at odd hours. Roughly one in four calls to this hotline arrives between 11pm and 6am. That is Charles Parharm’s own operational data from this line, and it made the case by itself.
There is nothing different about the overnight version of the call. The same questions get asked and the same information comes back at 2:40am as at 2:40pm. What changes is that you no longer have to burn a day of leave, step away from a machine, or take a call in a hospital stairwell to have it.
- Call after a night shift ends, before you sleep.
- Call on a holiday when everything else is closed.
- Call mid hitch, mid rotation, or on a random Wednesday off.
- Call during a meal break and be done before it is over.
- Call at 1am because that is when the question finally surfaced.
What Dana Does, and What Dana Does Not Do
Dana is an automated AI assistant. Dana is a system, not a person, and Max Mortgage states that plainly rather than letting anyone assume otherwise.
Here is the honest division of labor. Dana gathers the basics and gives you an idea of which loan program or programs may be worth exploring. Dana does not approve loans, does not deny loans, does not lock a rate, and does not make underwriting decisions. Prequalification is an early estimate based on what you describe on the call. It is not a commitment to lend, and nothing on that call guarantees an approval, a rate, or any particular outcome.
The decisions that require a licensed human get one. After your call, a licensed Max Mortgage team member reviews what came through and follows up during business hours to pick up where Dana left off.
Non-Traditional Schedules and Non-Traditional Income
Shift work often comes with income that does not look like a flat salary. Shift differentials. Overtime. Holiday premium pay. Per diem. Hitch pay. Call-back pay. A base wage that is modest next to what actually lands in the account.
The reassuring part is that lenders are used to this. Income that is not a flat salary is not automatically excluded. What generally matters is how long you have earned it and how consistently it shows up in your documentation. The specific rules vary by loan program and change over time, which is exactly why they are reviewed by a licensed loan officer against your actual paperwork rather than estimated from a blog post. Bring it up on the call and it gets flagged for that review.
The same goes for employment history. A steady record with one employer looks strong even when the hours are unusual. Working nights is not a mark against you. The Consumer Financial Protection Bureau publishes a useful plain-language overview of the homebuying process if you want to read ahead before you call.
What Actually Happens When You Call 504-399-4141
No paperwork is required for the first call. You do not need tax returns, pay stubs, or bank statements in front of you. It helps to have a rough idea of your income, your monthly debts, and whether you are looking to buy or refinance, but approximate answers are fine at this stage.
The call covers what you are trying to do, the general shape of your finances, and which programs may apply. FHA, VA, USDA, and DSCR are all on the table, along with general homebuying and refinance questions. Most calls take five to ten minutes. You hang up knowing more than you did, with no obligation attached.
One note for anyone calling about FHA, VA, or USDA loans. Max Mortgage is a private, independent mortgage broker. It is not a government agency and it is not affiliated with HUD, the Department of Veterans Affairs, or the USDA. Current loan limits, credit score thresholds, and down payment figures for those programs change, so they are covered on the call with current numbers rather than quoted here.
Holidays, Storm Season, and the Weeks Nobody Answers
Holiday coverage is its own category of scheduling problem. If you are the one working Thanksgiving, Christmas Eve, Mardi Gras, or a hurricane activation, the standard advice to just call during the week is not advice at all.
The hotline does not observe holidays. Neither does the question you are sitting with. If a quiet hour opens up on a holiday shift and you want to know whether buying a house is realistic next spring, that hour counts the same as any other.
Frequently Asked Questions
Can shift workers get a mortgage prequalification at night?
Yes. Max Mortgage operates a mortgage prequalification hotline at 504-399-4141 that answers 24 hours a day, including overnight, weekends, and holidays, so shift workers can call during their own waking hours.
Who answers the Max Mortgage hotline at 3am?
The hotline is answered by Dana, an automated AI assistant built by Max Mortgage. Dana is not a human being. A licensed Max Mortgage team member follows up after the call during business hours.
Does working nights or rotating shifts hurt my chances of buying a home?
Working nights or rotating shifts does not disqualify anyone from a home loan. Lenders look at documented income history and stability rather than the time of day the work is performed.
Does overtime or shift differential pay count toward qualifying for a mortgage?
Overtime and shift differential pay can sometimes be counted, depending on how long it has been earned and how consistently it appears in your documentation. The current rules for your situation are reviewed by a licensed loan officer, not by the hotline.
Does calling the hotline commit me to applying for a loan?
No. Calling 504-399-4141 does not commit you to applying for a loan, and prequalification is an early estimate rather than a commitment to lend.
What loan programs can the hotline discuss?
The hotline can discuss FHA, VA, USDA, and DSCR loan programs as well as general homebuying and refinance questions.
How long does a prequalification call take?
Most calls run about five to ten minutes, which is short enough to fit inside a meal break or a drive home.
Start With One Call, on Your Own Clock
You do not need to rearrange your life around a lender’s business hours to find out where you stand. Call 504-399-4141 whenever your schedule opens up, talk to Dana, and let a licensed team member take it from there. You can also read more about the programs Max Mortgage works with at maxxla.com.
Charles, Mortgage Loan Advisor with Max Mortgage, LLC. 20+ years in mortgage and real estate. NAMB Certified FHA Mortgage Professional.
Max Mortgage, LLC | NMLS #1446745
Charles Parharm | NMLS #1413036
Licensed to conduct residential mortgage business in applicable states. Loan programs, terms, and conditions are subject to change without notice. All loans are subject to approval. Equal Housing Opportunity.