If you are house hunting in Orleans, Jefferson, or St. Tammany Parish, a New Orleans FHA appraisal can feel like the biggest hurdle between you and the keys. Older homes here come with raised foundations, original wiring, and decades of small repairs, and an FHA appraiser is trained to flag anything that does not meet minimum property standards. Understanding what a New Orleans FHA appraisal actually checks for can save you weeks of back and forth with a seller, and it can keep your closing date on track.
Why a New Orleans FHA Appraisal Feels Stricter Than a Conventional One
FHA loans are backed by the federal government, so a New Orleans FHA appraisal does two jobs at once. The appraiser confirms the home’s market value, then checks that the property meets HUD’s minimum safety and livability standards. A conventional appraisal only looks at value. That second layer is why older homes in historic neighborhoods sometimes need repairs before a lender will finish underwriting, even when the home is priced fairly and the buyer is fully qualified.
Common Red Flags in a New Orleans FHA Appraisal on Older Homes
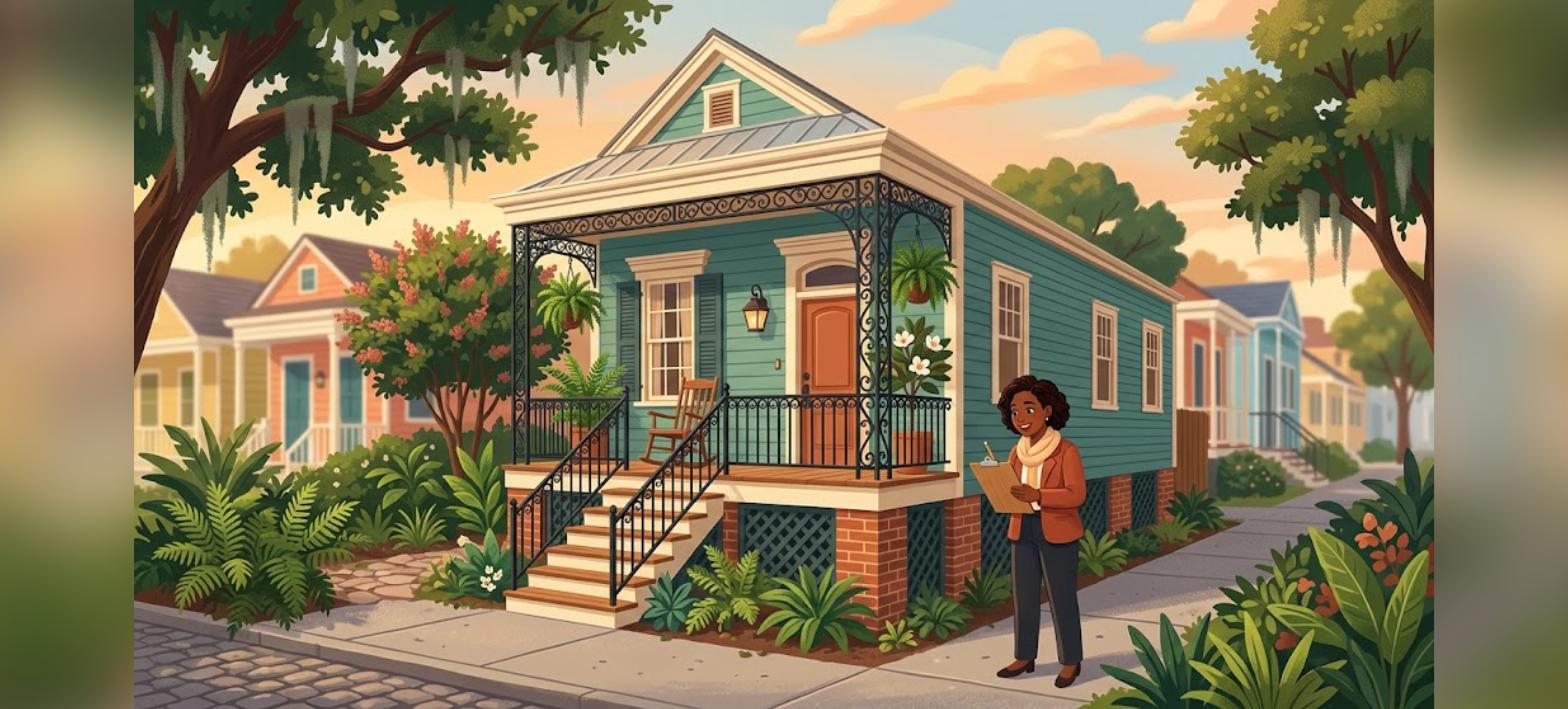
Much of New Orleans’ housing stock predates modern building codes, and that history shows up in nearly every New Orleans FHA appraisal on a shotgun house, camelback, or raised cottage. Appraisers commonly flag the following items.
- Peeling or flaking paint on homes built before 1978, due to lead-based paint rules
- Exposed or outdated wiring, especially knob-and-tube systems in unrenovated homes
- Missing handrails on exterior steps, common on raised New Orleans homes
- Roof damage or visible water staining inside the attic or ceilings
- Foundation cracks or signs of settling around piers
None of these automatically disqualify a home. They simply need to be corrected, documented, and re-inspected before your New Orleans FHA appraisal is finalized.
Crawl Spaces, Drainage, and Repairs Appraisers Enforce
Raised homes are common across New Orleans, and the crawl space underneath is one of the most overlooked parts of a New Orleans FHA appraisal. Appraisers require the crawl space to be free of debris, standing water, and stored materials. Years of accumulated storage under an older home is one of the most frequent repair items buyers run into.
Drainage is checked closely too. Do-it-yourself plumbing that empties directly under the house, rather than into the city sewer system, is a common issue in older New Orleans properties, and it must be corrected by a licensed plumber before an FHA loan can close. Catching these details early, ideally during your home inspection, gives you time to negotiate repairs with the seller instead of scrambling right before closing.
How Flood Zones Factor Into Your New Orleans FHA Appraisal
Much of the city sits at or below sea level, and flood zone designation affects more than your appraisal report. It affects whether flood insurance is required and how much your total monthly payment will run. A New Orleans FHA appraisal does not set your flood insurance premium, but the appraiser will note the flood zone, and your lender will use that information to determine coverage requirements. Buyers are often surprised that two similar homes a few blocks apart can carry very different insurance costs depending on their flood zone. Building that number into your budget before you make an offer prevents last-minute payment shock.
Preparing Your Offer for a Smooth New Orleans FHA Appraisal
A little preparation goes a long way toward a New Orleans FHA appraisal that closes on schedule. Before you write an offer on an older home, consider the following steps.
- Ask your agent about the home’s age, prior renovations, and known repair history
- Budget for a private home inspection in addition to the FHA appraisal, since they check different things
- Request seller-paid repairs as part of your negotiation when issues are likely
- Get a flood zone determination early so insurance costs are not a surprise
Sellers in New Orleans are generally familiar with FHA requirements, since FHA financing is common across the metro area. Most repair requests are resolved quickly once both sides understand what the appraisal is actually asking for.
Work With a Lender Who Knows New Orleans FHA Appraisal Rules
Not every lender spends their days working through the specific quirks of New Orleans housing stock. Choosing someone who understands how a New Orleans FHA appraisal plays out on a raised cottage in Mid-City or a shotgun double in Gentilly can be the difference between a stressful closing and a smooth one. A local lender can help you anticipate likely repair items before the appraiser ever walks through the door, and can guide you toward realistic timelines when repairs are needed.
For a closer look at current FHA loan limits and eligibility rules across the metro, see our 2026 guide to FHA loans in New Orleans and surrounding parishes. For the official minimum property standards appraisers follow, HUD’s appraisal and property requirements page is a good primary source to bookmark.
What These Repairs Typically Cost
Buyers often ask how much money to set aside for repairs before closing on an older home. Minor items like handrails, GFCI outlets, or a crawl space cleanout usually run a few hundred dollars total. Roof work, foundation repair, or a full electrical panel update can run into the thousands, depending on scope. Getting a licensed contractor’s estimate as soon as an item is flagged helps you negotiate with real numbers instead of guesswork. In many cases, sellers agree to complete the repair themselves or offer a closing credit, as long as the item does not affect the home’s habitability under HUD’s guidelines.
Frequently Asked Questions
Can I buy a fixer-upper with FHA financing? Yes, through the FHA 203(k) renovation loan, which wraps repair costs into the mortgage. It is a separate product from a standard FHA purchase loan and works well for buyers who want an older home with known deferred maintenance.
Who pays for the repairs an appraiser requires? That is negotiable between buyer and seller. Many sellers in this market already expect repair requests on FHA offers and build that expectation into their pricing strategy.
How long do repairs add to closing? Straightforward items like handrails or outlet fixes can be resolved in a few days. Larger issues, like foundation work, may add several weeks, so building extra time into your contract is smart when you know an FHA loan is involved.
Ready to Talk Through Your New Orleans FHA Appraisal Questions?
Every home is different, and every New Orleans FHA appraisal brings its own list of items to work through. If you are looking at an older home and want to know what to expect before you make an offer, reach out and we will walk through it together.
Prequalify anytime by calling our 24/7 prequalification hotline at 504-399-4141, or start your application anytime through our 24/7 application hotline at 504-332-0888.
Charles, Mortgage Loan Advisor with Max Mortgage, LLC. 20+ years in mortgage and real estate. NAMB Certified FHA Mortgage Professional.