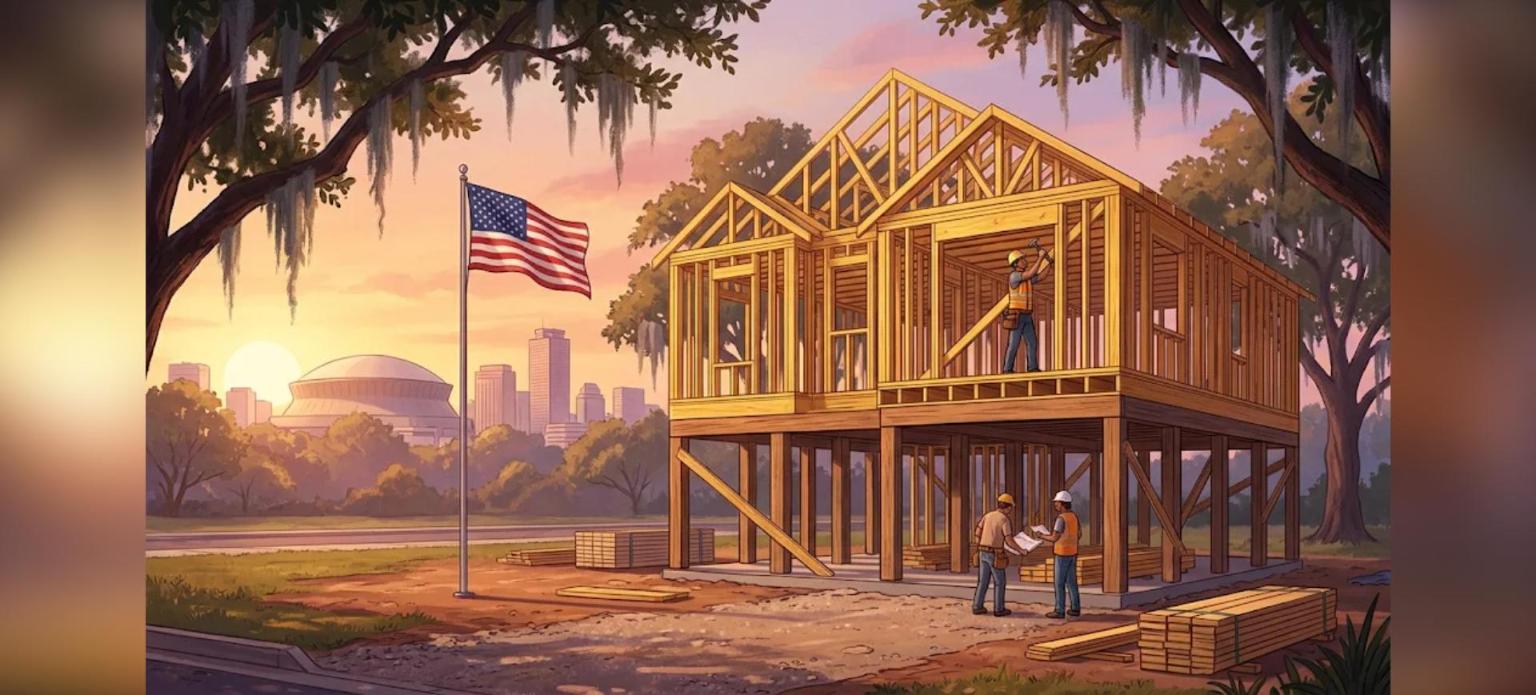
A New Orleans VA construction loan lets Veterans and Active Duty Military build a brand new home with one closing, zero down payment, and no PMI. If you have been scrolling listings in Metairie, Kenner, the Westbank, or the Northshore and not finding the right house, building may be the better move. This guide walks you through the process step by step, written only for those who have served or are serving.
I am Charles, Mortgage Loan Advisor with Max Mortgage, LLC. 20+ years in mortgage and real estate. NAMB Certified FHA Mortgage Professional. I help service members across the New Orleans area use their VA benefit the smart way, and the New Orleans VA construction loan, known as the VA One-Time Close, is one of the most powerful tools in that benefit.
What a New Orleans VA Construction Loan Actually Is
The VA One-Time Close (OTC) combines your construction financing and your permanent mortgage into a single loan. You sign once, you pay closing costs once, and when the home is finished the loan simply converts to your permanent VA mortgage.
Compare that to the old two-loan route. A short-term construction loan, then a second closing, a second appraisal, and a second round of qualifying. If rates or your income change mid-build, that second closing can get painful. The OTC removes that risk.
Key benefits Veterans and Active Duty Military see with this program:
- $0 down payment for eligible borrowers with full entitlement
- No private mortgage insurance, ever
- One application, one approval, one closing
- The lot can often be included in the loan, or land you already own can count toward the deal
- Funding fee exemption for Veterans receiving VA compensation for a service-connected disability
Step 1: Confirm Your Certificate of Eligibility and Entitlement
Everything starts with your Certificate of Eligibility (COE). Veterans, Active Duty service members, and many Guard and Reserve members qualify based on time in service. Your lender can usually pull the COE electronically in minutes.
Entitlement matters too. With full entitlement, there is no VA loan limit on how much you can borrow with zero down, as long as you qualify for the payment. If you still have a VA loan on another property, for example from a prior PCS, you may have partial entitlement. In that case a small down payment may be needed on a higher priced build.
Step 2: Pick a VA-Registered Builder
This is the step that trips up the most Veterans. For any New Orleans VA construction loan, your builder must have a VA builder ID and be approved by the lender. A great local builder who has never done VA work can still get registered, but it takes time and paperwork, so start that conversation early.
When you interview builders around New Orleans, ask:
- Do you already have a VA builder ID?
- Are you licensed with the Louisiana State Licensing Board for Contractors?
- Do you offer a fixed price contract with a clear draw schedule?
- What warranty do you provide at completion?
- How many homes have you built in this parish, and how did they handle elevation and drainage?
Step 3: Choose the Right Lot With Flood Risk in Mind
Every New Orleans VA construction loan needs a plan for water. Before you fall in love with a lot in St. Tammany, Jefferson, St. Bernard, St. Charles, or Plaquemines Parish, check its flood zone on the FEMA Flood Map Service Center.
If the lot sits in a Special Flood Hazard Area, flood insurance will be required. Each parish also sets its own elevation rules for new construction, often based on base flood elevation plus extra freeboard. Building above those minimums costs more up front, but it can lower flood insurance premiums for the life of the loan. Ask your builder to price elevation into the contract from day one.
Step 4: Get Your Plans, Contract, and Appraisal Lined Up
With a New Orleans VA construction loan, the VA appraisal is based on your plans and specs, meaning the value the home will have when finished. You will need a signed construction contract, house plans, a materials list, and a budget that includes the lot.
The finished home must meet VA Minimum Property Requirements. That means safe, structurally sound, and sanitary, with working utilities and proper drainage. A good VA builder already knows these standards and designs to them.
Step 5: Understand the VA Funding Fee
Most VA borrowers pay a one-time funding fee, which can be rolled into the loan. For a first-time VA user putting less than 5% down, it is currently 2.15% of the loan amount. Subsequent use with less than 5% down is higher. Putting money down lowers the fee.
Here is the big one. Veterans who receive VA compensation for a service-connected disability are exempt from the funding fee. Certain Active Duty Purple Heart recipients and eligible surviving spouses are also exempt. On a $350,000 build, that exemption can save you more than $7,500. You can review the current fee table on the official VA funding fee page.
Step 6: Close Once and Start Building
After your New Orleans VA construction loan is approved, you close a single time. The builder then gets paid in draws as work is completed and inspected: foundation, framing, dry-in, and so on. You do not have to manage the money yourself.
Most single-family builds in the area run roughly 6 to 12 months depending on the builder, weather, permits, and parish inspections. Hurricane season can slow things down, so build some breathing room into your plans, especially if you have a PCS date or lease ending.
Step 7: Final Inspection and Conversion
When the home is done, a final inspection confirms it was built to the plans and meets VA Minimum Property Requirements. Once that clears, your loan converts to your permanent VA mortgage. No second closing. You get the keys and start making regular payments.
Is a New Orleans VA Construction Loan Right for You?
It is a strong fit if you want a newer, more energy efficient, better elevated home than what is on the resale market, you have a clear idea of where you want to live, and you have a VA-registered builder in mind. Lenders commonly look for steady income, a manageable debt-to-income ratio, and a solid credit history for construction loans.
It may not be the best fit if you need to move in the next 60 days or you are still deciding between several parishes. In that case, a standard VA purchase may serve you better for now.
Common Questions From New Orleans Veterans
Can I use a New Orleans VA construction loan on the Northshore? Yes. The New Orleans area including St. Tammany, Jefferson, and surrounding parishes within about 50 miles is fair game, as long as your builder and lot qualify.
Can I be my own builder? Generally no. The VA One-Time Close requires a licensed, VA-registered builder.
Do I make payments during construction? It depends on the lender and loan structure. Ask about interest during construction before you sign so there are no surprises.
Want more background? Read our New Orleans VA one-time close guide for Vets or browse all of our VA loan articles.
Start Your New Orleans VA Construction Loan Today
You earned this benefit. Let us help you use a New Orleans VA construction loan to build the home you actually want. Call anytime, day or night:
- 24/7 Prequalification Hotline: 504-399-4141
- 24/7 Application Hotline: 504-332-0888
Charles, Mortgage Loan Advisor with Max Mortgage, LLC. 20+ years in mortgage and real estate. NAMB Certified FHA Mortgage Professional.
Equal Housing Opportunity. This is not a commitment to lend or extend credit. Restrictions may apply. Information and/or data is subject to change without notice. All loans are subject to credit approval. Not all loans or products are available in all states. Licensed in LA, TX, MS, AL, FL. Max Mortgage, LLC NMLS #1446745