PCS mortgage prequalification is available 24 hours a day at 504-399-4141, the Max Mortgage prequalification hotline. The line is answered by Dana, an automated AI assistant, not a person. Dana helps a service member or a military family get an early read on which loan programs may fit their situation, at any hour, including the middle of the night, weekends, and holidays. A licensed Max Mortgage team member follows up after the call. Prequalification is an early estimate and not a commitment to lend.
Orders rarely arrive at a convenient moment. The report date is fixed, the house hunting window is short, and the person who needs answers is often several time zones away from a lender’s front desk. That gap is the reason this line exists.
Why PCS orders compress a mortgage timeline
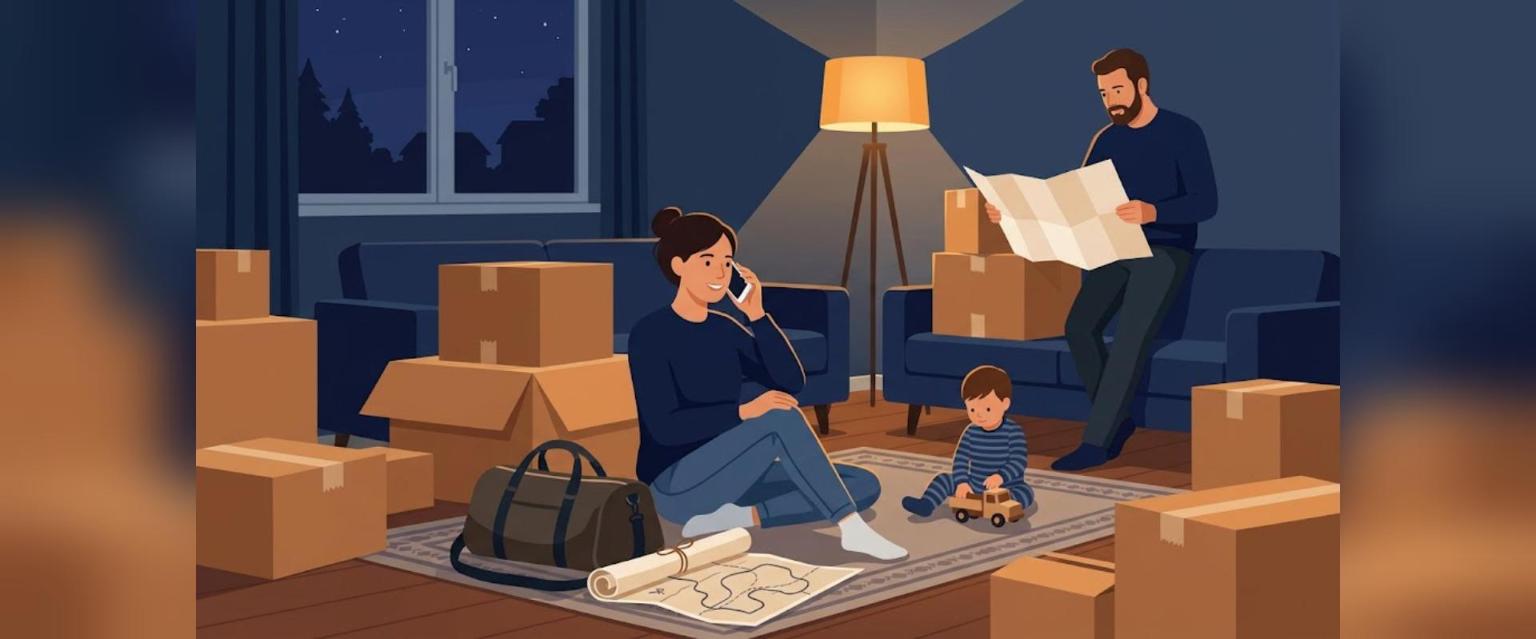
A permanent change of station turns a housing decision into a scheduling problem. You may have a few weeks between the day orders are confirmed and the day you are expected to report. Inside that window you may need to research a market you have never lived in, line up leave, coordinate a spouse’s job, sort out schools, and decide whether buying makes sense at all.
Most mortgage offices answer the phone about eight hours a day, five days a week. A PCS timeline does not respect that schedule. The practical result is that families lose days waiting for a callback, and days matter when a report date is fixed. Being able to ask the first round of questions immediately, rather than next Tuesday morning, changes what is possible inside the window.
PCS mortgage prequalification that matches duty hours
The hotline at 504-399-4141 is answered every hour of every day. That is not a marketing flourish. Roughly one in four calls to this line come in between 11pm and 6am. Those are shift workers, night owls, people standing watch, and people calling from a place where the middle of the night on the Gulf Coast is the middle of their afternoon.
For a service member that matters in specific ways. You may be coming off a twelve hour shift. You may be in the field with one reliable window to make a call. You may be stationed overseas with a large offset from Louisiana time. Dana does not need you to call during business hours, and she does not need an appointment.
What Dana can cover on a PCS call
Dana is built for the first conversation, the one where you are still working out what is even on the table.
- Which loan programs may fit your situation, including FHA, VA, USDA, DSCR for investment property, and general purchase or refinance questions
- What kinds of income and documentation usually come up in a mortgage file
- Plain language explanations of terms you have run into while researching
- What a next step with a licensed Max Mortgage team member would look like
- Questions about buying in the New Orleans metro area or in another state where Max Mortgage is licensed
Max Mortgage, LLC is a private, independent mortgage broker. It is not a government agency and it is not affiliated with HUD, the Department of Veterans Affairs, or the United States Department of Agriculture. Program rules for FHA, VA, and USDA loans are set by those agencies and they change over time. Current figures such as loan limits, credit expectations, and down payment requirements are discussed on the call against what is actually in effect that day, rather than quoted from an article that may be months old. For the agency’s own description of the VA home loan benefit, the Department of Veterans Affairs publishes it at va.gov.
What Dana does not do
This part matters, and it is worth stating plainly.
- Dana is an automated AI assistant. She is not a person and is never presented as one.
- Dana does not approve or deny loans and does not make underwriting decisions.
- Dana does not lock a rate or quote a guaranteed payment.
- Dana does not promise an outcome, an approval, or a closing date.
What Dana does is give you an organized starting point and hand the conversation to a licensed human being who can take it further. Every loan is subject to credit approval and to the lender guidelines in effect at the time of application.
What to have ready before you dial
Approximate answers are fine. Nobody expects you to dig a pay statement out of a moving box at one in the morning.
- A rough idea of household income before taxes
- A rough idea of monthly debt payments such as a car note, student loans, or credit cards
- Where you are moving and your report date, even approximately
- Whether you plan to buy, rent first, or keep your current home
- Roughly what you have available for a down payment and closing costs
If you only know half of these, call anyway. Dana can work with partial information and tell you which gaps actually matter. Numbers on a first call are estimates, and nothing you say on that call locks you into anything.
Buying at the new duty station, or renting first
There is no universally correct answer here, and anyone who tells you otherwise is selling something. The honest version is that it depends on how long you expect to be stationed there, what the local rental market looks like, how much time you have before the report date, and whether you would be comfortable managing a property from a distance if you move again in two or three years.
Some families buy right away. Some rent for a year, learn the area, then buy. Some keep the house at the last duty station and rent it out, which turns the question into an investment property conversation with its own set of considerations. Dana can walk through all three paths without pushing you toward one of them. If you are weighing the move itself more than the loan, the post on relocation mortgage prequalification for out of state buyers covers similar ground from a civilian angle.
For the spouse handling the move alone
In plenty of PCS moves, one person is already gone and the other is handling the housing search, the packers, and the kids. This hotline is open to whoever is doing that work. You do not need the service member on the line to ask which programs might fit, and you do not need to wait until you are both in the same time zone to get started.
Frequently Asked Questions
Can I get mortgage prequalification while I am on PCS orders?
Yes. The Max Mortgage prequalification hotline at 504-399-4141 is answered every hour of every day, so a service member or military spouse working against PCS orders can get an early read on loan options at any time, including nights, weekends, and holidays.
What is the phone number for the Max Mortgage 24/7 prequalification hotline?
The Max Mortgage 24/7 mortgage prequalification hotline number is 504-399-4141.
Is Dana a real person?
No. Dana is an automated AI assistant used by Max Mortgage, LLC to handle prequalification calls. Dana is not a human being, and a licensed Max Mortgage team member follows up after the call.
Does Dana approve loans?
No. Dana does not approve or deny loans, does not lock rates, and does not make underwriting decisions. Dana gives callers an early idea of which loan programs may fit their situation, and all loans are subject to credit approval.
Can I call the hotline from overseas or from another time zone?
Yes. The hotline at 504-399-4141 is answered 24 hours a day, so callers in any time zone, including service members stationed overseas, can reach it whenever it is convenient for them.
What information do I need before I call about a PCS move?
Approximate answers are enough to start. A rough idea of household income, monthly debt payments, your destination and report date, and what you have available for a down payment is helpful, but the call can begin with partial information.
Does Max Mortgage handle VA loans?
Yes. Max Mortgage, LLC works with VA loans along with FHA, USDA, and DSCR loan programs. Max Mortgage is a private, independent mortgage broker and is not a government agency or affiliated with the Department of Veterans Affairs.
Is prequalification the same as an approval?
No. Prequalification is an early estimate based on information you provide, and it is not a commitment to lend. All loans are subject to credit approval and to the loan program guidelines in effect at the time of application.
About the author: Charles, Mortgage Loan Advisor with Max Mortgage, LLC. 20+ years in mortgage and real estate. NAMB Certified FHA Mortgage Professional.
Max Mortgage, LLC | NMLS #1446745
Charles Parharm | NMLS #1413036
Licensed to conduct residential mortgage business in applicable states. Loan programs, terms, and conditions are subject to change without notice. All loans are subject to approval. Equal Housing Opportunity.