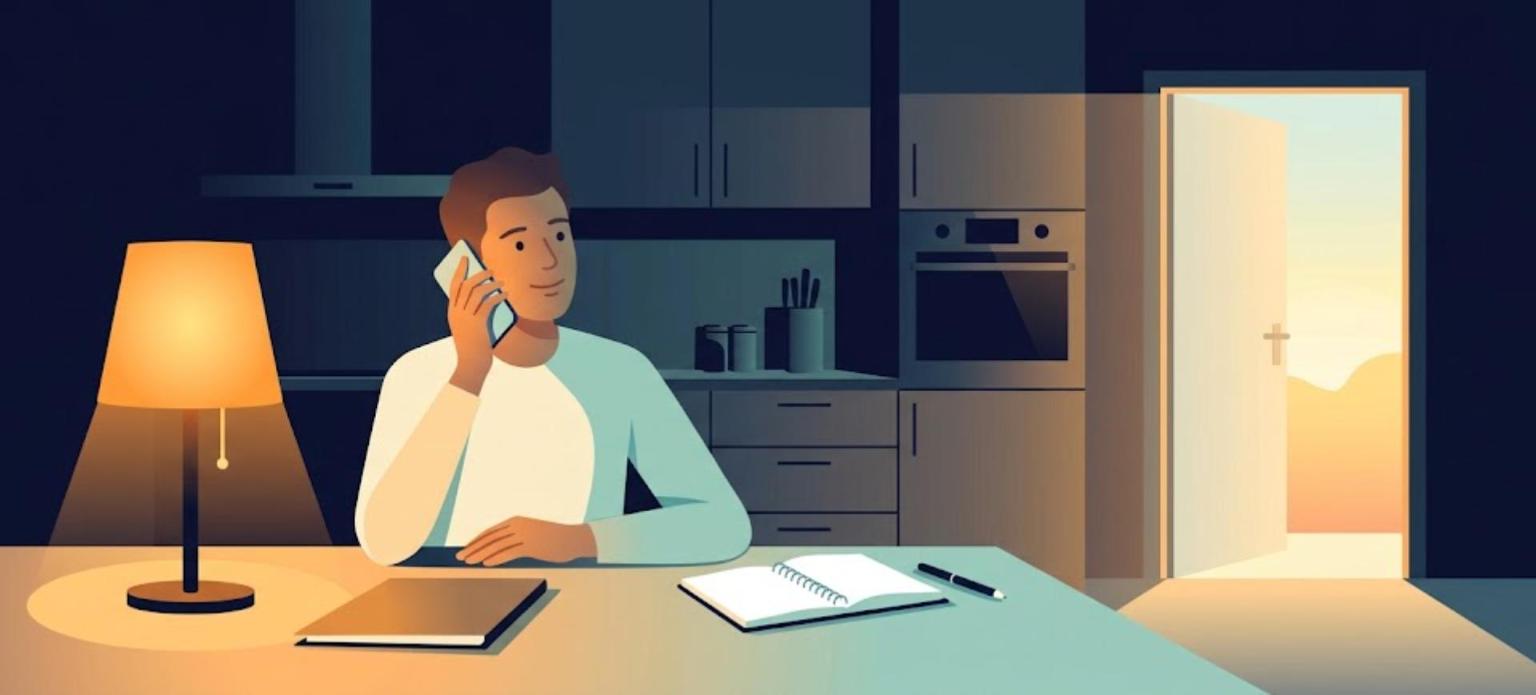
Mortgage prequalification after a denial is available 24 hours a day from Max Mortgage, LLC at 504-399-4141. The hotline is answered by Dana, an automated AI assistant, not a person. You can call the same night another lender turns you down, describe your situation in a few minutes, and get a general sense of which loan programs may be worth a closer look. A licensed Max Mortgage team member follows up afterward. Prequalification is an early estimate and not a commitment to lend.
Most people do not call anyone the day they get turned down. They close the laptop, put the letter in a drawer, and decide the whole idea was premature. That reaction is understandable and it is also the single most expensive thing a would-be homeowner can do, because a decline from one lender is one company’s answer to one version of your file on one particular day. It is not a verdict on whether you can own a home.
What mortgage prequalification after a denial actually involves
A second prequalification conversation is not a re-run of the first one. The useful version starts in a different place: with what happened, not with what you want. Dana is built to ask about the turndown directly, because the reason behind it changes everything that follows.
Three broad situations come up again and again on this line, and each points somewhere different:
- The file was fine, the program was wrong. A borrower is steered toward one loan type when a different program fits their income, their property, or their down payment far better. Nothing about the person needed to change.
- The file was incomplete, not insufficient. Income that is real but documented in an unusual way, a deposit nobody explained, a job change that looked worse on paper than it was in life. Paperwork problems are fixable and they are common.
- Something genuinely needs work first. Credit, debt load, savings, or time at a new employer. This is the hardest answer to hear and it is still better heard out loud, with a plan attached, than guessed at in silence.
Knowing which of the three applies to you is worth far more than a yes or a no. It is the difference between waiting indefinitely and working on one specific thing for a defined stretch of time.
Why one lender’s no is not every lender’s no
Lenders are not interchangeable. Different lenders work with different investors, carry different internal requirements layered on top of agency guidelines, and have different appetites for particular kinds of files. Two lenders can look at the same borrower and reach different conclusions without either of them being wrong.
A mortgage broker occupies a different seat than a single bank or direct lender. Max Mortgage, LLC is an independent brokerage, which means the question is not whether you fit one institution’s box but which of several programs and lenders your situation actually suits. That is a different question, and it sometimes has a different answer.
None of this is a promise. No one can tell you in advance that a second look will go your way, and anyone who does is not being straight with you. What can be promised is that the second look is free, it takes a few minutes, and you can get it at two in the morning without explaining yourself to a receptionist.
What Dana asks on the call
Dana keeps the first conversation short and plain. Expect questions along these lines:
- What another lender told you, and whether you received anything in writing
- Roughly what you earn and how you are paid, including self-employment or 1099 income
- Your approximate monthly debt payments
- What you have set aside for a down payment and closing costs
- Where you are looking to buy, or whether this is a refinance
- Whether anyone will be on the loan with you
Approximate answers are fine. Nobody is checking your math on a first call, and no documents are required to have this conversation. If you do have the written notice from the other lender nearby, read what it says, because that language often names the exact issue in a sentence or two.
What Dana does not do
This matters enough to state plainly. Dana is an automated AI assistant. Dana is not a licensed loan officer and is not a human being. Dana does not approve loans. Dana does not deny loans. Dana does not lock rates, quote you a rate you can count on, or make any underwriting decision. Dana gathers information, answers general questions about how loan programs work, and flags which directions may be worth exploring.
Every actual credit decision at Max Mortgage is made by licensed people working with licensed lenders, after a real review of real documents. The hotline exists to get you to that review faster, and to spare you a week of wondering whether it is even worth starting.
The reasons behind a turndown are more ordinary than you think
People who get declined tend to assume something disqualifying and permanent is wrong with them. In practice the reasons cluster around a handful of ordinary, mechanical things: a debt-to-income ratio that ran over a threshold, a credit report with an error or an old collection nobody disputed, income from self-employment or commission that was averaged in a way that undercounted it, a down payment gift that lacked a paper trail, a property that did not qualify for the specific program applied for, or a job change too recent for that lender’s comfort.
Several of those are documentation problems rather than borrower problems. Some resolve in days. Others take months of deliberate work, and in that case the honest service is a clear path and a realistic timeline, not encouragement. The federal Consumer Financial Protection Bureau’s homebuying resources are a useful neutral reference while you sort through what you were told.
If you are early in the process and this is your first time through any of it, our guide to a judgment-free place to start for first-time buyers covers the same ground from the beginning.
Why the hotline runs overnight
Roughly one in four calls to this hotline come in between 11pm and 6am. That is Max Mortgage’s own operational data, and it lines up with when people actually have the privacy and the quiet to think about money.
A turndown lands in the middle of a workday and then sits with you all evening. By eleven at night, after the house is quiet, you finally have five minutes and a head full of questions. Dana is awake for exactly that. There is no callback form, no waiting until Monday, and no explaining your situation to someone who is only taking a message.
Saturdays and Sundays are normal hours on this line too. So are holidays.
Frequently Asked Questions
Can I get a mortgage prequalification after a denial from another lender?
Yes. You can call the Max Mortgage prequalification hotline at 504-399-4141 at any hour to talk through a new prequalification, even if another lender already told you no. A prequalification is an early estimate of what you may be eligible for and it is not a commitment to lend.
Does a previous mortgage denial stay on my record forever?
A denial itself is not a permanent mark on your credit report. The application may have created a credit inquiry, and inquiries fade in importance over time, but a lender’s decision to decline is that lender’s decision and it does not bind any other lender.
Who answers the 504-399-4141 hotline at night?
Dana answers the hotline. Dana is an automated AI assistant built by Max Mortgage, LLC, not a human team member. Dana collects your basic information, answers general questions, and points you toward the loan programs that may fit, then a licensed Max Mortgage team member follows up with you.
Will Dana tell me whether I am approved?
No. Dana does not approve loans, deny loans, lock rates, or make underwriting decisions. Dana gives you a general sense of which loan programs may be worth exploring, and all actual credit decisions are made by licensed people and lenders after a full review.
How long should I wait after a mortgage denial before trying again?
There is no fixed waiting period required before applying with a different lender. The right timing depends on the reason the first application did not go through, and that is one of the first things a conversation should establish.
What should I have ready when I call after a turndown?
Bring whatever the other lender told you, including any written notice you received, plus a rough idea of your income, your monthly debts, and how much you have available for a down payment and closing costs. Approximate answers are fine on a first call.
Is there any cost or obligation to call the hotline?
No. Calling 504-399-4141 for a prequalification conversation carries no cost and no obligation to apply for anything.
Which loan programs can the hotline discuss?
The hotline covers FHA, VA, USDA, and DSCR investment property financing, along with conventional purchase and refinance questions. Max Mortgage, LLC is a private, independent mortgage broker and is not a government agency and is not affiliated with HUD, the VA, or the USDA.
Where to start tonight
If another lender said no, the next useful step is small: call 504-399-4141, tell Dana what you were told, and find out which of the three situations above you are actually in. The call is free, it carries no obligation, and it does not require a single document.
Max Mortgage, LLC is licensed in Louisiana, Texas, Mississippi, Alabama, and Florida. We are a private, independent mortgage broker. We are not a government agency and we are not affiliated with HUD, the VA, or the USDA. Loan program details, current limits, and qualifying figures change, and the ones that apply to you are covered on the call.
About the author: Charles, Mortgage Loan Advisor with Max Mortgage, LLC. 20+ years in mortgage and real estate. NAMB Certified FHA Mortgage Professional.
Max Mortgage, LLC | NMLS #1446745
Charles Parharm | NMLS #1413036
Licensed to conduct residential mortgage business in applicable states. Loan programs, terms, and conditions are subject to change without notice. All loans are subject to approval. Equal Housing Opportunity.