New Orleans DSCR 1-4 unit loans are the financing tool most local investors reach for once they move past a single rental house and start looking at shotgun doubles, triplexes, and small fourplexes. The city’s housing stock is full of these property types, and within roughly 50 miles of downtown, from Metairie and Kenner to Chalmette, Slidell, and Covington, small multifamily buildings trade hands constantly.
Understanding how New Orleans DSCR 1-4 unit loans work, and what they actually require, helps investors and first-time investors move faster when the right property shows up.
What Counts as a 1-4 Unit Property in New Orleans
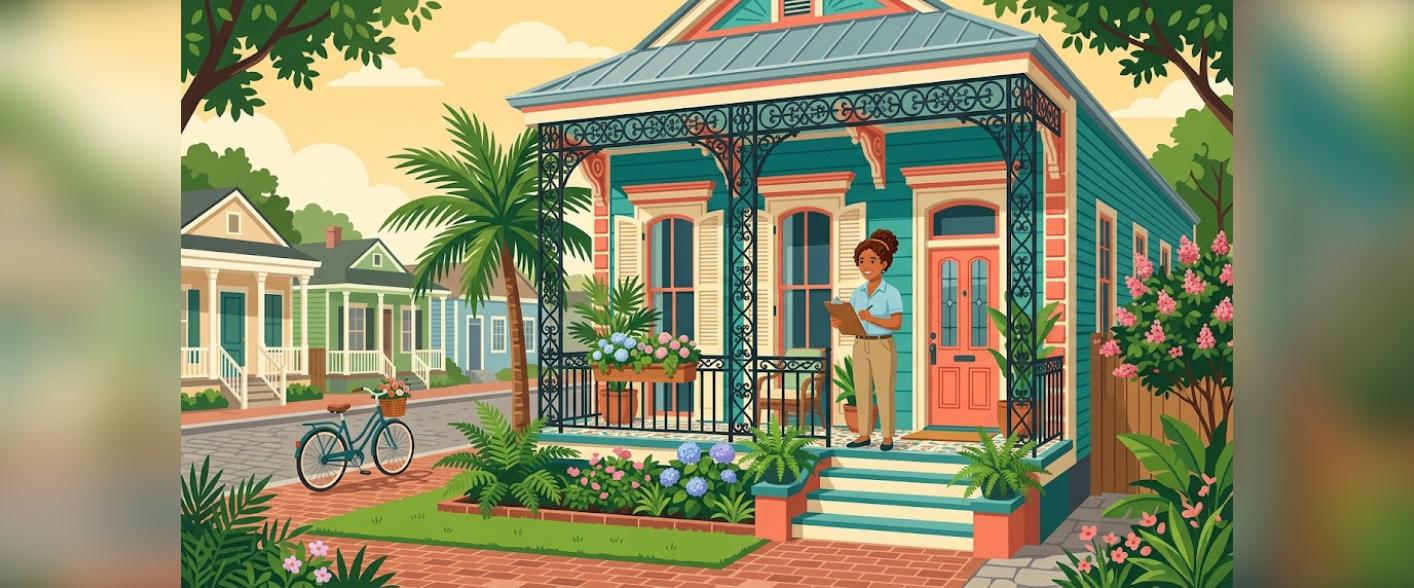
New Orleans real estate has a distinct mix of 1-4 unit housing. Shotgun singles get converted into shotgun doubles, camelback cottages sit two units deep, and classic double shotguns already function as built-in duplexes. Neighborhoods like Gentilly, the 7th Ward, Bayou St. John, Bywater, and Mid-City all have concentrations of these properties, and triplex or fourplex conversions show up in older sections of Mid-City and
Central City as well. For lending purposes, any property with one to four units, whether it started that way or was legally converted, falls under residential 1-4 unit financing rather than commercial multifamily rules that kick in at five units and above.
How New Orleans DSCR 1-4 Unit Loans Work
A DSCR loan, short for debt service coverage ratio loan, qualifies a rental property based on the income the property produces rather than the borrower’s personal tax returns or pay stubs. The lender divides the property’s gross monthly rent by its full monthly payment, including principal, interest, taxes, insurance, and any HOA or association dues, to get the debt service coverage ratio. Most lenders want to see a ratio at or above 1.0, and pricing typically improves once that ratio reaches 1.25 or higher, commonly described as a 1.25x DSCR. This
structure is what makes New Orleans DSCR 1-4 unit loans useful for investors and first-time investors who do not want their personal income statement driving the underwriting decision on a rental purchase.
Down Payment and Reserve Requirements for 1-4 Unit DSCR Loans
Down payment expectations vary by property type and borrower profile. A single-family rental typically calls for around 20 percent down, while 2 to 4 unit properties commonly require closer to 25 percent, though some programs allow 20 percent down on a 2-4 unit deal when the DSCR and credit profile are both strong.
Reserves for New Orleans DSCR 1-4 unit loans matter just as much as the down payment. Most DSCR lenders want to see liquid reserves equal to roughly three to six months of the property’s full monthly payment held in the bank after closing, and that requirement can run higher for a short-term rental strategy. Credit expectations generally start in the 660 to 680 range, with better pricing available above 700.
Flood Insurance and Conversion Costs to Budget For
For New Orleans DSCR 1-4 unit loans, flood zones add a real line item to any 1-4 unit deal. Annual flood premiums in the $2,000 to $4,000 range are common on investment property in flood-prone parts of the metro, and that expense pulls the DSCR down if it is not built into the pro forma from the start. For properties
For properties being converted, such as turning a shotgun single into a double or adding a legal third unit, permits from the city and compliance with New Orleans’s Comprehensive Zoning Ordinance are required before the additional unit can be counted as rentable square footage or income for underwriting. Skipping that step is one of the most common ways an investor’s numbers stop matching what a lender will actually finance.
What New Orleans Investors Should Have Ready
A few things speed up any application for New Orleans DSCR 1-4 unit loans: a market rent estimate or signed lease for each unit, a realistic insurance estimate that includes flood coverage where the property sits in a flood zone, proof of reserves covering several months of payments, and documentation on any unit count changes, including permits if the property was legally converted from a single to a double or from a double to a triplex.
Investors working across the wider 50-mile radius, from the Northshore down to Chalmette, should also confirm short-term rental permit status block by block, since New Orleans regulations on commercial short-term rental use vary significantly by neighborhood.
For a broader look at how DSCR financing applies across both small rentals and larger apartment buildings in this market, see our New Orleans DSCR and investor loans guide. Background on how duplex conversion rules work locally is also covered well by Steadily’s guide to New Orleans duplex conversion laws.
Working With a Local Advisor
Charles, Mortgage Loan Advisor with Max Mortgage, LLC. 20+ years in mortgage and real estate. NAMB Certified FHA Mortgage Professional.
Charles works with investors and first-time investors across the New Orleans metro who are financing shotgun doubles, triplexes, and fourplexes with New Orleans DSCR 1-4 unit loans. If you are comparing a single rental against a small multifamily purchase, a conversation about reserves, flood costs, and down payment options up front can save a lot of guesswork once an offer is already in.
24/7 prequalification hotline: 504-399-4141
24/7 application hotline: 504-332-0888
Equal Housing Opportunity. This is not a commitment to lend or extend credit. Restrictions may apply. Information and/or data is subject to change without notice. All loans are subject to credit approval. Not all loans or products are available in all states. Licensed in LA, TX, MS, AL, FL. Max Mortgage, LLC NMLS #1446745